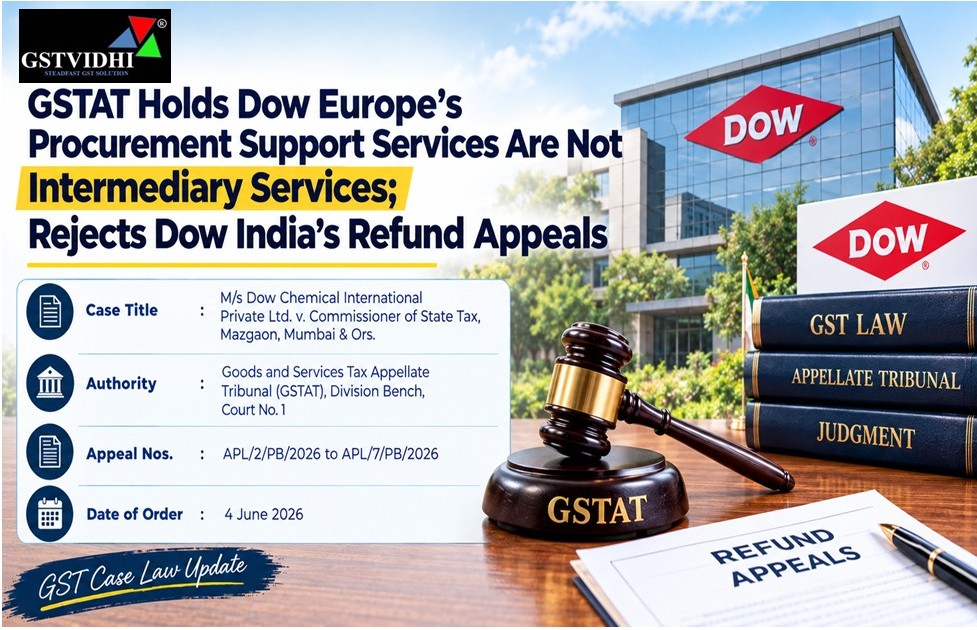
GSTAT Holds Dow Europe’s Procurement Support Services
Are Not Intermediary Services; Rejects Dow India’s Refund Appeals
Summary of
the Case
The Goods and Services
Tax Appellate Tribunal (GSTAT) dismissed the appeals filed by Dow Chemical
International Private Limited, holding that the procurement support services
provided by its Switzerland-based group entity, Dow Europe GmbH, were not “intermediary
services” under Section 2(13) of the IGST Act, 2017.
The Tribunal held that
Dow Europe provided services on its own account as a centralised procurement
hub for the Dow Group. Accordingly, the services were treated as an import of
services, with the place of supply in India. The Tribunal therefore upheld the
rejection of Dow India’s refund claims.
Background
and Facts
Dow Chemical
International Private Limited entered into a Procurement Agreement dated 1 July
2021 with Dow Europe GmbH, Switzerland, a related entity within the Dow Group.
Under the agreement, Dow
Europe performed various procurement-related activities, including:
- Identifying, selecting and approving
foreign suppliers.
- Negotiating procurement terms and
conditions.
- Assisting in the procurement of
materials and components.
- Reviewing and signing contracts and
purchase orders.
- Supporting the procurement process
throughout its lifecycle.
During January 2022 to
June 2022, Dow India paid IGST under the Reverse Charge Mechanism (RCM) on the
consideration paid to Dow Europe. Subsequently, Dow India reversed the related
Input Tax Credit (ITC) and applied for refunds of the IGST paid.
The total refund claimed
across the six tax periods was ₹13,41,89,994. The refund applications
were rejected by the adjudicating authority, and the rejection was upheld by
the First Appellate Authority. Dow India then approached GSTAT.
Key Issues
Before the Tribunal
The Tribunal considered
the following principal issues:
1. Whether
the services provided by Dow Europe qualified as intermediary services under
Section 2(13) of the IGST Act.
2. Whether
Section 13(8)(b), as applicable during the relevant period, determined the
place of supply as Switzerland.
3. Whether
Dow India was entitled to a refund of the IGST paid under RCM.
Submissions
of Dow India
Dow India argued that Dow
Europe merely facilitated the purchase of goods between Dow India and
independent foreign suppliers. According to the company, the main supply was
made by the foreign suppliers to Dow India, while Dow Europe performed the
ancillary function of arranging or facilitating that supply.
It relied on Section
2(13) of the IGST Act and CBIC Circular No. 159/15/2021-GST, contending that
the procurement activities satisfied the requirements for intermediary
services.
Dow India also argued
that the fact that the parties were related entities and that Dow Europe acted
as an independent contractor did not, by itself, determine the nature of the
services.
Findings of
the Tribunal
A. Three parties were
involved, but that was not sufficient
The Tribunal accepted
that the arrangement involved three parties: Dow India, Dow Europe and the
foreign suppliers. However, the involvement of three parties alone did not
establish that the services were intermediary services.
B. Procurement services
were provided on Dow Europe’s own account
The Tribunal found that
Dow Europe and Dow India were part of the same Dow Group, ultimately connected
to Dow Inc. Dow Europe functioned as a centralised procurement hub and provided
core procurement services to group companies across the world.
The Tribunal held that
the services provided by Dow Europe were not merely ancillary services for
facilitating a separate supply. Rather, Dow Europe was providing its own
procurement services as an independent contractor.
C. The services did not
qualify as intermediary services
After examining Section
2(13) of the IGST Act and the principles explained in CBIC Circular No.
159/15/2021-GST, the Tribunal concluded that the services provided by Dow
Europe did not fall within the definition of intermediary services.
The Tribunal also
referred to the principles considered in Columbia Sportswear and BlackBerry,
relating to services provided by an independent service provider on its own
account.
D. Place of supply was
held to be in India
Since the services were
not intermediary services, the Tribunal held that Section 13(8)(b) of the IGST
Act did not apply. The services were treated as an import of services, with the
place of supply in India.
E. Refund could not be
rejected merely as an afterthought
The Tribunal disagreed
with the First Appellate Authority’s observation that Dow India’s refund claim
was an afterthought merely because the company had initially paid GST.
It observed that Section
54 of the CGST Act and Rule 89 of the CGST Rules provide a statutory mechanism
for claiming refunds. Therefore, a refund application cannot be rejected merely
on the ground that the taxpayer had earlier paid tax under a mistaken understanding.
However, this observation
did not result in relief for Dow India because the Tribunal ultimately held
that the services were taxable as an import of services.
Final
Decision
The Tribunal held that
the procurement support services provided by Dow Europe were not intermediary
services and that the place of supply was in India.
Accordingly, the Tribunal
answered the issues against Dow India and in favour of the Revenue. All six
appeals were dismissed, and the orders of the First Appellate Authority
rejecting the refund claims were confirmed.
Conclusion
The ruling highlights
that the classification of services as intermediary services depends on the
actual nature of the activities performed and whether the service provider
merely facilitates another supply or provides services on its own account.
The Tribunal also
clarified that a refund claim should not be rejected merely because the
taxpayer initially paid tax under a mistaken understanding. However, the
taxpayer must still establish that the tax paid is refundable under the
applicable provisions of law.
Disclaimer: All the Information is strictly for educational purposes and on the basis of our best understanding of laws & not binding on anyone.
Click here